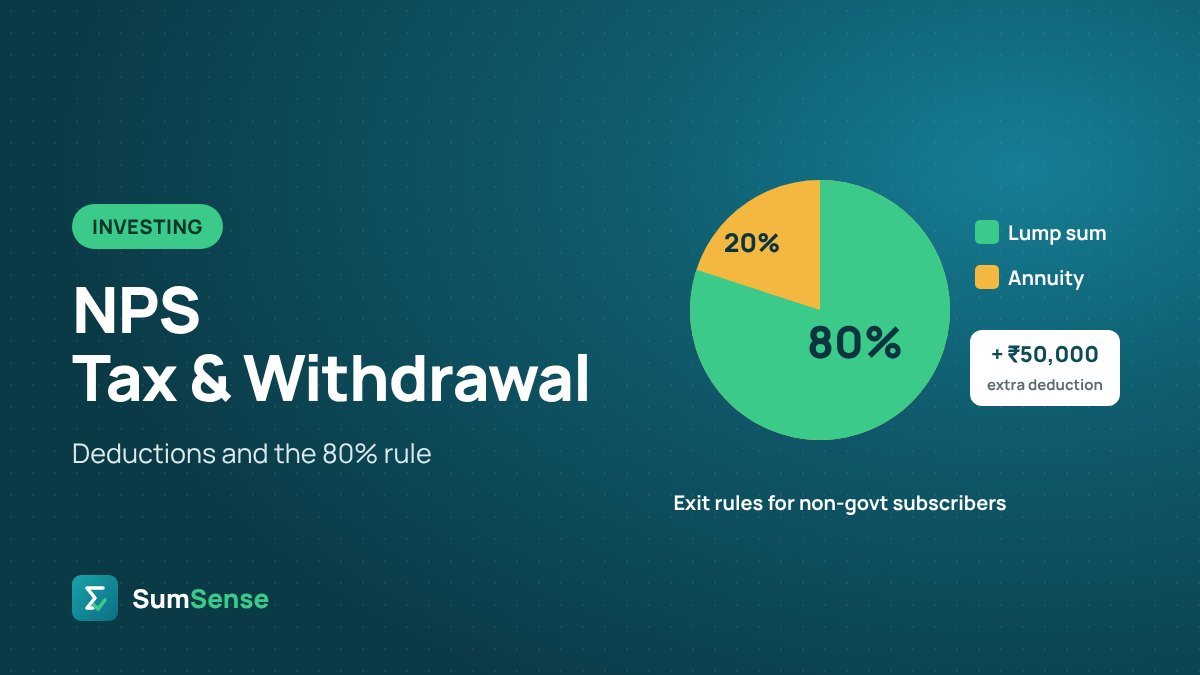
The National Pension System (NPS) gives an extra ₹50,000 deduction beyond the ₹1.5 lakh limit under the old regime, and employer contributions are deductible under both regimes. Since PFRDA’s December 2025 changes, non-government subscribers can take up to 80% of the corpus as a lump sum at exit, with at least 20% used for an annuity.
Tax benefits
| Contribution | Deduction | Regime |
|---|---|---|
| Your own contribution | Within ₹1.5 lakh (Section 123, old 80C) | Old only |
| Extra own contribution | Up to ₹50,000 more (old 80CCD(1B)) | Old only |
| Employer’s contribution | Up to 14% of basic + DA (new regime); 10% for private employees in the old regime | Both |
The employer contribution is the one benefit that also works in the new regime. If your employer offers it, ask to restructure part of your CTC into NPS.
Withdrawal at exit (non-government subscribers)
| Corpus at exit | What you can do |
|---|---|
| Up to ₹8 lakh | Withdraw everything; annuity optional |
| ₹8 lakh – ₹12 lakh | Withdraw up to ₹6 lakh with the rest in an annuity or phased payout, or up to 80% with at least 20% in an annuity |
| Above ₹12 lakh | Up to 80% lump sum or phased withdrawal; at least 20% in an annuity |
Normal exit is at 60, or after 15 years in the scheme, whichever comes first.
Leaving early
- Corpus up to ₹5 lakh: withdraw it all.
- Above ₹5 lakh: up to 20% lump sum; at least 80% must buy an annuity.
- Partial withdrawal after 3 years: up to 25% of your own contributions, for purposes such as children’s education or marriage, buying a house or medical treatment – up to four times before 60.
Tax at withdrawal
- Up to 60% of the corpus taken at exit is tax-free.
- Anything above 60% may be taxable – check the treatment in the year you exit.
- The annuity (pension) you receive is taxed as income every year.
- Partial withdrawals within the 25% limit are tax-free.
Is NPS right for you?
- Good for: disciplined retirement saving, low fund charges, and the extra tax deduction if you are in the old regime.
- Less good for: money you might need before 60, or if you dislike buying an annuity.
- Choose your equity share carefully – up to 75% for most private subscribers.
Estimate your retirement corpus with the retirement calculator. The Income-tax Act, 2025 renumbered the NPS sections, so your Form 16 for tax year 2026-27 will show new section numbers. See the Section 123 list for other old-regime deductions.
Frequently asked questions
How much NPS can I withdraw at 60?
Non-government subscribers with a corpus above ₹12 lakh can take up to 80% as a lump sum; at least 20% must buy an annuity. Smaller corpora have more flexible options.
Is the NPS lump sum tax-free?
Up to 60% of the corpus taken at exit is tax-free. The annuity income is taxed every year.
Which NPS benefit works in the new tax regime?
The deduction for your employer’s NPS contribution, up to 14% of basic plus DA.