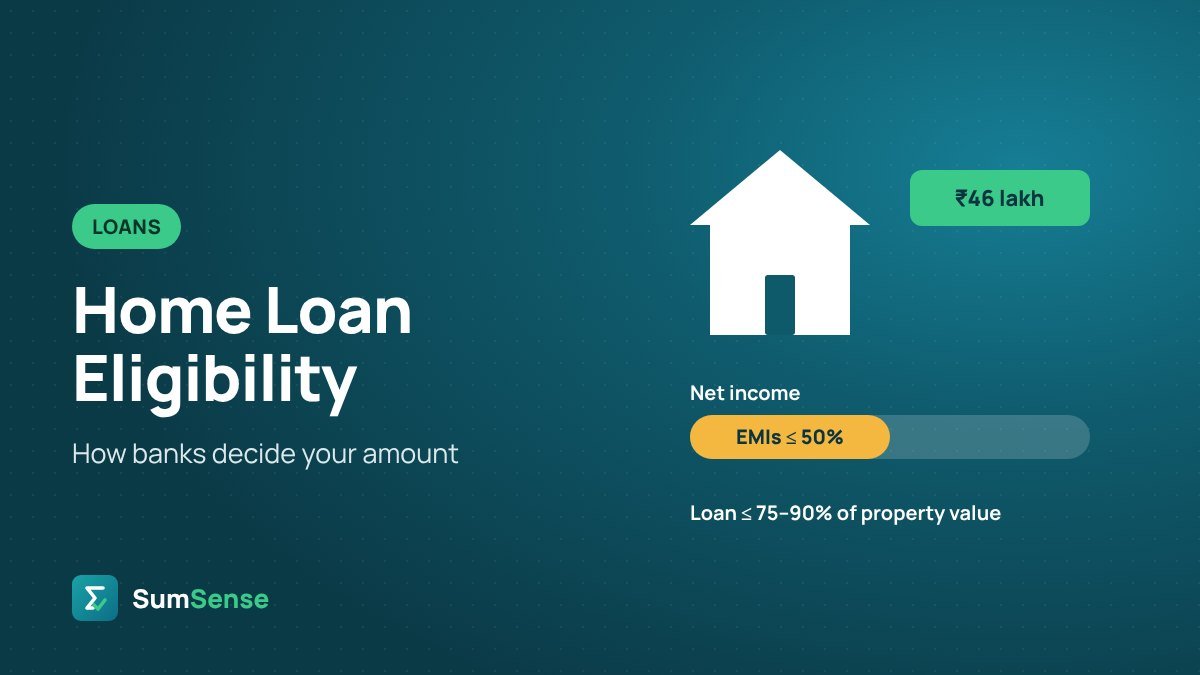
Most banks let your total EMIs take up 50–60% of your net monthly income. The loan is also capped at 75–90% of the property’s value. Your age, credit score and existing loans then fine-tune the final amount.
The two limits
1. Income limit (FOIR). FOIR – fixed obligations to income ratio – is your total EMIs divided by your net monthly income. Lenders usually allow 50% for moderate incomes and up to 60–65% for higher incomes.
2. Property limit (LTV). RBI caps how much of the property’s value a bank can lend:
| Loan amount | Maximum loan as % of property value |
|---|---|
| Up to ₹30 lakh | 90% |
| ₹30 lakh – ₹75 lakh | 80% |
| Above ₹75 lakh | 75% |
Stamp duty and registration are usually not included in the property value, so you pay them yourself.
Worked example
| Item | Value |
|---|---|
| Net monthly income | ₹1,00,000 |
| Existing EMI (car loan) | ₹10,000 |
| EMIs allowed at 50% FOIR | ₹50,000 |
| Available for home loan EMI | ₹40,000 |
| EMI per ₹1 lakh at 8.5% for 20 years | about ₹868 |
| Eligible loan | about ₹46 lakh |
Check your own number with the home loan eligibility calculator and the EMI with the home loan EMI calculator.
What else affects eligibility
- Age: the loan usually has to end by 60 (salaried) or 65–70 (self-employed), which can shorten the tenure and the amount.
- Credit score: 750 or more gets the best rates; below about 650 may mean rejection – see how to improve your CIBIL score.
- Job and income stability: lenders prefer 2–3 years of steady employment or business records.
- Interest rate: the RBI raised the repo rate to 5.50% on 7 October 2026; repo-linked home loans may get costlier, which lowers the loan a given EMI can support.
How to borrow more
- Add an earning co-applicant (spouse or parent) to combine incomes.
- Close small loans or credit card balances before applying.
- Choose a longer tenure to lower the EMI – but you’ll pay more interest overall.
- Declare all regular income, such as rent or variable pay, with proof.
Before you stretch, check that the EMI leaves room for savings. Our EMI guide and home loan tax benefits can help, and compare current offers on home loan interest rates.
Frequently asked questions
How do banks decide home loan eligibility?
Mainly by FOIR: total EMIs are usually capped at 50–60% of net monthly income. The loan is also capped at 75–90% of the property value.
How can I increase my home loan eligibility?
Add an earning co-applicant, close small loans first, choose a longer tenure, and keep your credit score above 750.